Budget Calendar

Screenshots
Details
- Rating
- 189.00 reviews
- Version
- 1.69
- Developer
- MiShell Software Systems
Analysis by Norviv
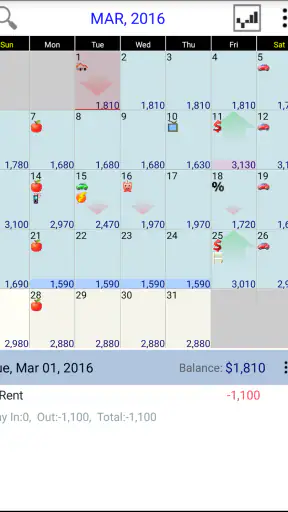
Managing money on a phone usually means opening a spreadsheet, searching through a banking app, or trying to remember which bills are due before the next paycheck. Budget Calendar takes a more visual route. It is a finance app from MiShell Software Systems that puts budgeting into a calendar-style view, making the timing of income and expenses the main part of the experience. After spending time with it, I found that its appeal is less about flashy automation and more about seeing whether my money has to survive the space between one date and the next.
That difference matters. A monthly total can look comfortable while the actual week ahead is difficult because several payments arrive together. A calendar exposes that pressure immediately. Its strongest idea is turning a budget into a sequence of financial events rather than a single balance. For people who plan around paydays, rent, subscriptions, school costs, or irregular household spending, that approach can feel much more practical than a conventional category list.
Planning money around real dates
The first thing I noticed is that this is not an app I would open only to check a current account balance. It is better understood as a planning surface. I use the calendar to think ahead: when money comes in, which obligations follow, and how much room remains before the next income event. That makes it useful before spending happens, not just afterward.
The calendar format also changes how I interpret familiar expenses. A utility payment is no longer just part of a monthly category; it becomes something that occupies a particular point in the month. The same applies to rent, transport, groceries, insurance, and occasional purchases. This encourages a more realistic question: “Can I cover what is coming next?” rather than “Did I stay under my monthly target?”
I found that especially helpful for people paid on a fixed schedule but managing expenses that do not arrive evenly. If a paycheck lands near the beginning of the month and several large bills follow soon after, the visual spacing makes the pressure easy to spot. Someone with variable income can also use the calendar to mark expected money and avoid treating uncertain funds as if they were already available.
The app is aimed at a broad audience, and its Everyone content rating makes it approachable for ordinary household planning. Still, approachable does not mean completely effortless. The value depends on entering dependable information and keeping it current. If I add only a few expenses, the calendar gives me an incomplete picture. It works best when I treat setup as a short financial organizing session rather than expecting an instant answer after installation.
What the calendar view changes
Traditional budgeting apps often begin with categories. They ask how much was spent on food, transport, entertainment, or bills. That is useful for reviewing behavior, but it can hide timing problems. Budget Calendar starts from the opposite direction: the date is the organizing principle. Categories still matter, but the order of events becomes easier to understand.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Compared with a spreadsheet, I find this less intimidating for quick planning. A spreadsheet can be more flexible, especially for custom formulas and detailed reporting, but it also demands more structure from the user. Here, the act of placing money-related items on a calendar gives the plan a natural rhythm. I can look at a week and understand the pressure without scanning rows and columns.
Compared with a banking app, the distinction is even clearer. A banking app is usually strongest at showing transactions and balances from a financial institution. This tool is more useful for deciding what those transactions mean in the days ahead. I would not replace a bank’s security and account information with it; I would use the calendar as a planning layer beside everyday banking.
It also differs from a simple reminder app. A reminder can tell me that a bill is due, but it does not naturally encourage me to consider the surrounding income and expenses. The calendar approach makes the relationship between dates the important part. That is the non-obvious benefit: the app can reveal cash-flow congestion even when every individual payment seems manageable.
Using it during ordinary mobile routines
This is the kind of finance app I would use in short sessions while moving through the day. I might check the coming week before shopping, review the next payday while commuting, or add an expense shortly after making a purchase. The calendar structure suits a phone because I do not need to build a large report every time I want a quick sense of what is ahead.
A realistic example is a household preparing for the first week after payday. Rent may already be planned, a recurring service may be due a few days later, and a grocery trip is still ahead. Looking only at the available balance could create false confidence. Looking at the calendar makes it easier to reserve money mentally for those known events before deciding what can be spent freely.
I also see value for someone who shares financial responsibilities with a partner, even if only one person maintains the plan. The calendar can act as a conversation aid: instead of discussing vague concerns about “spending too much,” both people can look at the sequence of upcoming obligations. That does not solve disagreements or replace a shared account system, but it gives the discussion a concrete timeline.
For students or younger users, the same method can help with irregular costs such as transport, course materials, or social plans. The app is not limited to a formal family budget. Its date-centered design works whenever money arrives and leaves in a pattern that is easier to understand visually than through totals alone.
Where connectivity affects the experience
Connectivity becomes relevant whenever I need to obtain the app, update it, or rely on information that may come from outside the app itself. Budget planning is personal, so I prefer to prepare entries when I have a stable connection and then avoid making important financial decisions based on a hurried or incomplete session. The calendar is most useful when the information displayed is current and trustworthy.
I would be cautious about assuming that every part of the experience behaves identically without a network connection. The available product details do not establish an offline workflow, so I would not treat the app as a guaranteed no-signal budgeting tool. If I were traveling, underground, or dealing with unreliable mobile service, I would make sure my important planning work was already in place rather than waiting until the last moment to enter it.
This matters more for a budget calendar than for a casual notes app. A missed update can affect how I interpret the days ahead. If I add a new bill only after connectivity returns, the earlier view may have encouraged spending that was no longer sensible. My practical habit would be to update the calendar during a reliable connection, especially before a shopping trip or a period with several payments due.
There is also a privacy-minded reason to avoid unnecessary network activity. Financial planning can reveal routines, obligations, and household timing. I would use a trusted connection when handling the app and avoid entering sensitive account credentials into any budgeting tool unless I clearly understood why they were needed. The app’s value does not require me to treat it as a replacement for secure banking access.
Recovering from mistakes and missed updates
No budget remains perfect for long. A payment changes, an expected expense disappears, or an unplanned purchase shifts the rest of the week. The important question is not whether the calendar can predict life perfectly; it is whether I can recover without abandoning the plan. I found the calendar concept useful because a change in one date naturally prompts me to inspect the nearby events as well.
My preferred workflow is to review the next few days after any meaningful change. If an expense is higher than expected, I look at what follows it rather than adjusting only a monthly total. That helps identify which discretionary purchases should wait. This is a more practical recovery method than staring at an overall budget number that may still look acceptable.
Missed entries are a bigger weakness. A calendar cannot warn me about an expense I never recorded. If I use the app casually for a week and then try to reconstruct everything from memory, the result will be less reliable. I would keep a simple habit: add a purchase soon after it happens, then do a short review at the end of the week. The second pass catches forgotten small items without turning budgeting into a daily chore.
Connectivity can complicate recovery if I am trying to make changes while service is unstable. I would avoid repeatedly tapping through an important update and assuming it was saved. Instead, I would return when the connection is dependable and confirm that the calendar reflects the change before relying on it. That is a general safe practice, but it is particularly important when the app becomes the reference point for upcoming bills.
Another useful recovery technique is to separate certainty from expectation. I would mark regular obligations confidently, but I would treat uncertain income or possible purchases more carefully. A calendar can make a planned event look definite simply because it has a date. Keeping that distinction in mind prevents the visual layout from creating more confidence than the underlying information deserves.
Making the app less demanding on data
Budgeting does not need constant online activity to be useful, but the way I use the phone can still affect data consumption. I would avoid reopening the app repeatedly just to glance at the same calendar. A better routine is to review the upcoming period at deliberate moments: before shopping, after income arrives, and during a weekly reset. That gives the app a clear role instead of turning it into a nervous checking habit.
I would also prepare larger edits when connected to a reliable network. Adding several recurring items, correcting a group of dates, or rebuilding a month is easier when I am not relying on weak mobile service. Short, intentional sessions reduce frustration and make it less likely that I will enter partial information.
The app’s relatively focused purpose helps here. It is not trying to be a social feed, a news reader, or a constantly refreshing dashboard. I can approach it as a personal planning tool and keep my use narrow. That is better for both attention and data-conscious habits: open it with a question in mind, make the necessary change, and leave with a clearer plan.
I would still keep a separate secure record of essential banking details and account access. A calendar budget is a planning aid, not a reason to place every piece of financial information in one mobile application. The most sensible setup is to use it for dates, expected amounts, and spending decisions while checking actual balances through the appropriate financial service.
Who will benefit, and who should choose something else
I would recommend Budget Calendar to someone who thinks in pay cycles and due dates. It is especially suitable for users who feel that ordinary category budgets do not explain why a month becomes difficult. People with recurring bills, uneven expenses, or a desire to plan before spending can get more from the calendar than from a basic expense log.
It is also a good fit for someone who dislikes spreadsheets but still wants more structure than a notes app. The visual timeline lowers the barrier to planning. I do not need to design formulas before I can begin thinking about the next few days. That simplicity is a strength when the goal is awareness and timing rather than detailed financial analysis.
I would skip it if I wanted automatic account synchronization, advanced investment tracking, extensive reports, or a complete household finance platform. A dedicated banking or financial management service may be better for users who need live balances, transaction imports, tax-oriented records, or complex category analysis. Likewise, a spreadsheet remains the stronger choice for people who enjoy building custom models and comparing many scenarios.
There is a trade-off in choosing the calendar approach. It makes timing clear, but it does not remove the discipline of entering information. Users who want the app to discover every transaction automatically may find the experience too hands-on. Users who want to understand the month as a sequence of commitments may see that same hands-on quality as the reason to use it.
Version, cost, and day-to-day expectations
The app is currently at version 1.69 and works on Android from version 7.0 onward. It was released on May 17, 2013, and its long presence suggests a focused product rather than a newly launched experiment. I would check device compatibility before installing, particularly on an older phone, but the minimum operating-system requirement is not demanding by current standards.
Budget Calendar costs $4.95, so the decision is straightforward: it makes sense when the calendar method matches the way I need to plan. I would rather pay once for a focused tool I actually use than install several free apps that scatter reminders, notes, and spending records across different places. On the other hand, someone who only wants occasional bill reminders may find the purchase unnecessary.
The app has an average rating of 4.8 from 481 ratings, with 189 written reviews, and has passed 10K+ installs. Those figures indicate a small but positive user base rather than a mass-market finance platform. I would interpret that as a sign that the app serves a particular budgeting preference well, not as proof that it will suit every financial routine.
MiShell Software Systems has kept the product’s identity clear: the emphasis is on planning money through a calendar. That focus is valuable because it avoids overwhelming the user with unrelated financial tools. It also means I need to be realistic about its role. I would use it alongside secure banking access, not as the sole source of truth for balances or transactions.
My connectivity verdict
After using the app as a date-based planning tool, I see its main strength in the moments when I stop thinking about money as one monthly number. The calendar makes upcoming pressure visible, helps me place spending in context, and encourages earlier decisions. It is particularly helpful on a phone because a short look at the next few days can be more revealing than a long category report.
Connectivity does not define the whole experience, but it does shape responsible use. I would update the calendar on a dependable connection, avoid assuming offline behavior that has not been established, and verify important changes before acting on them. Those habits keep a useful planning tool from becoming a source of false certainty.
My recommendation is clear: choose Budget Calendar if timing is the part of budgeting you struggle with most. It is a sensible purchase for people who want a compact, visual way to coordinate income and expenses, and it is less suitable for anyone seeking automatic banking data or sophisticated financial analysis. In the right hands, its simple calendar idea is not a limitation; it is the reason the upcoming month finally starts to make sense.
Frequently Asked Questions
01What is Budget Calendar and how does it work?
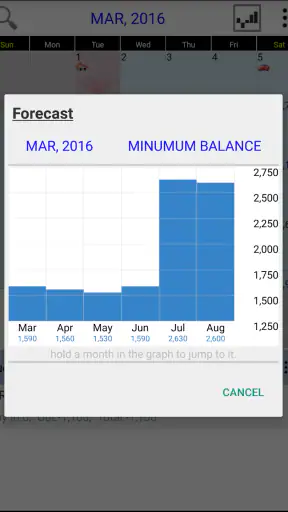
Budget Calendar is a personal finance app that combines a calendar view with budgeting tools. After entering your income, bills, subscriptions, and planned expenses, you can see when money is expected to come in and go out. This layout makes it easier to anticipate low-balance periods, organize recurring payments, and plan spending around your actual cash flow.
02Is Budget Calendar suitable for beginners who have never used a budgeting app?
Yes, Budget Calendar can be useful for beginners because its calendar-based interface presents financial information in a familiar format. Instead of relying only on charts or complicated reports, you can add transactions and recurring payments to specific dates. However, users still need to enter accurate information and review their budget regularly for the forecasts to remain reliable.
03Can Budget Calendar track recurring bills, subscriptions, and income?
The app is designed to help organize recurring financial events such as rent, utilities, loan payments, subscriptions, salary, and other regular income. Adding these items allows the calendar to project upcoming cash flow automatically. Before downloading, check the current app version and store listing to confirm which recurrence options, reminders, and automation features are included.
04Does Budget Calendar connect to bank accounts, and is my financial information safe?
Bank synchronization and privacy features may vary depending on the platform, region, and version of Budget Calendar. Some users may need to enter transactions manually, while others may have access to integrations or import tools. Before adding sensitive information, review the app’s privacy policy, permissions, data-handling details, and whether financial data is encrypted or shared with third parties.
05Is Budget Calendar free to download, or does it require a subscription?
Budget Calendar may be available as a free download while offering optional paid features, in-app purchases, or a subscription for advanced budgeting tools. Pricing and included features can differ between Android and iOS. We recommend checking the official store page before installing, especially if you want features such as unlimited accounts, cloud backup, detailed reports, or an ad-free experience.


